Market Notes, Issue #14, July 29, 2026
The Drought
Here is what the last four issues never did. They measured the frenzy from four angles, a million over asking, the buyers who moved one neighborhood over, the decoder for what an overbid actually reads, the pressure that spilled into condos and TICs, and not one of them named a cause. The cause is supply. Owners in San Francisco stopped listing, and every number that follows is the arithmetic of that.
By David Juarez, Level Up Group · Compass · Published July 29, 2026
Data source POTM, governed SFAR MLS data
Start with the answer and then let me show the work. There is almost nothing to buy. This scoreboard has now taken four passes at the same market from four directions. One counted the sales that closed a million over asking in June. One followed the buyers who kept losing and went looking a neighborhood over. One pulled apart the overbid percentage and showed how much of it reads as pricing strategy rather than raw demand. One tracked the pressure as it moved into the condos and TICs that live like houses. Each of those described the shape of the frenzy. None of them explained why it exists. The refreshed data finally does, and the explanation is dull in the best way.
Zero point seven months
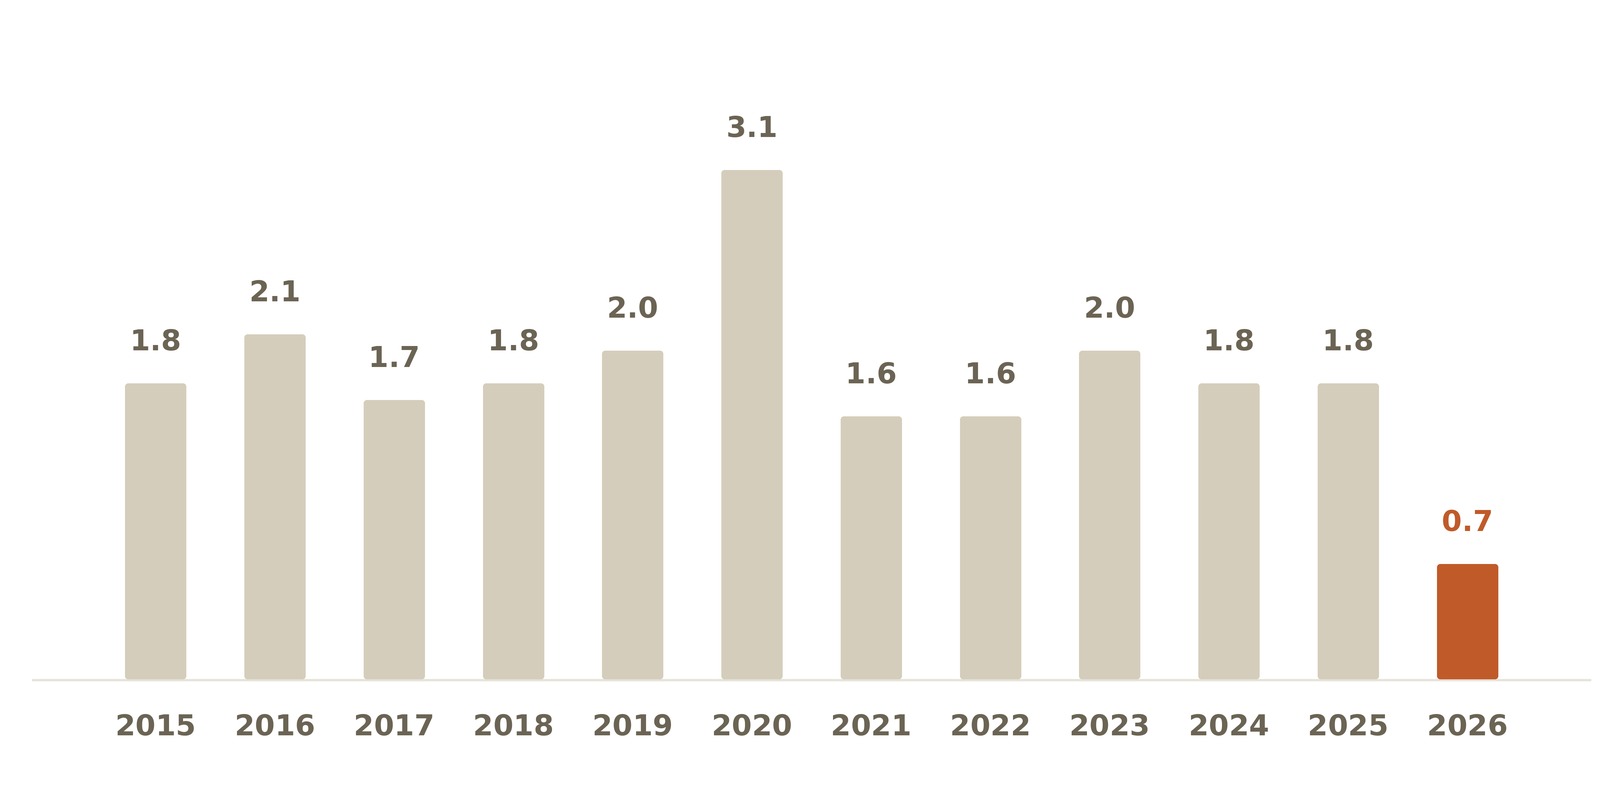
San Francisco houses sat at 0.7 months of supply in June. Read that as roughly three weeks of homes on the market, and it is the lowest June figure in at least twenty years. The series starts in 2005, so that is the entire record we have to compare against. Months of supply is the cleanest scarcity measure available, and it answers one question. At the pace homes are currently selling, how long before every listing on the market is gone. Most people call four to six months balanced. The hot springs of 2021 and 2022 were the tightest recent Junes on the board and they still held 1.6 months, so we are sitting at less than half of the last extreme. Houses are running near one tenth of a balanced market. That is not a tight market. It is a different one.
It is not only houses
Condos and townhomes came in at 1.7 months in June, the second-lowest June in the record. TICs came in at 1.1. A year ago those two lanes were sitting at 3.9 and 4.1, which is to say a buyer then had roughly twice the choice a buyer has today. Every property type in the city has been cut by more than half in twelve months. That changes how you should read the last issue. Pressure did not move into condos and TICs because those lanes were open. It moved there because nothing was open, and it had to go somewhere.
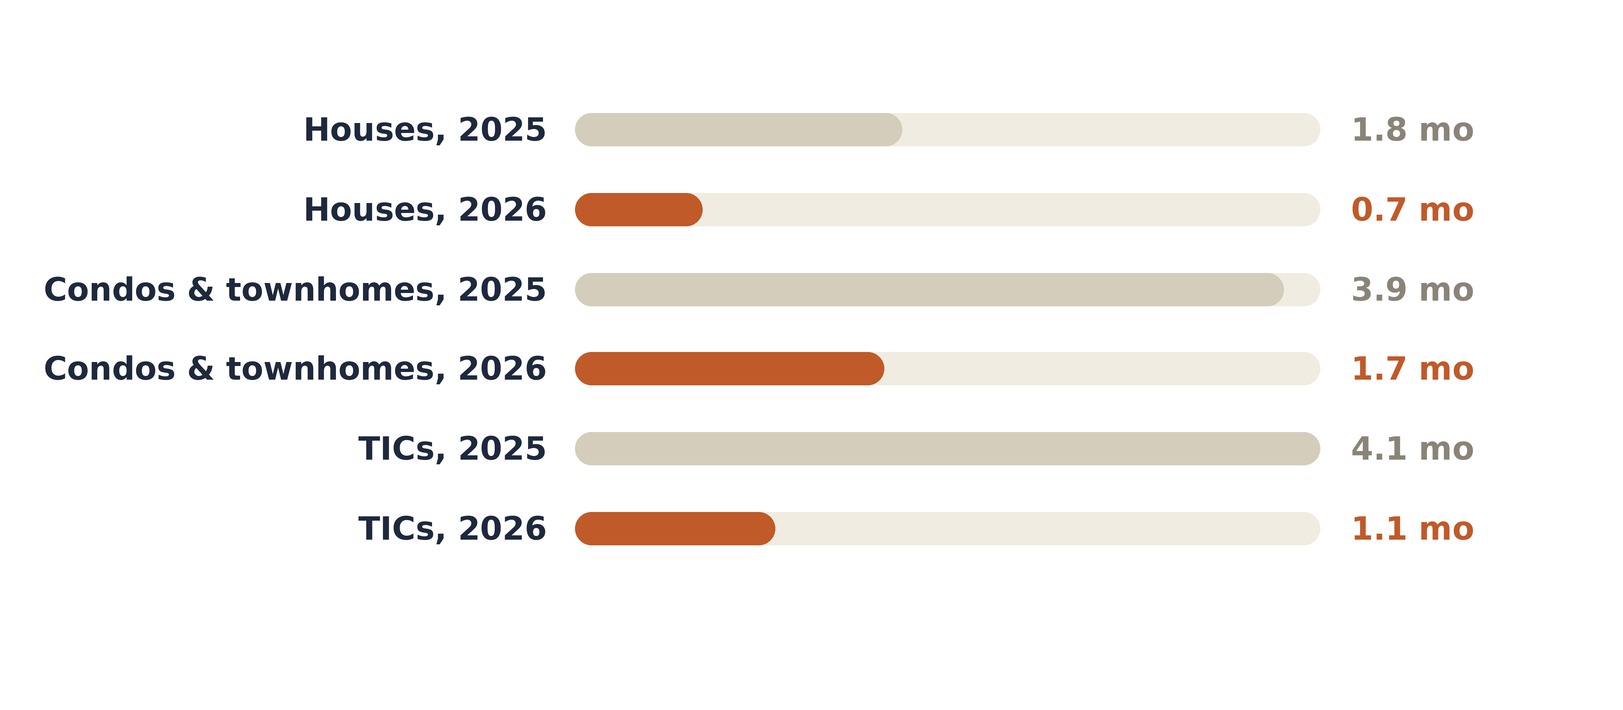
Now count the listings
Months of supply also falls when sales speed up, so I would not rest the argument on it alone. The raw listing count is the independent check, and it says the same thing. This May, San Francisco had 214 single-family homes active. In May a year earlier it had 390. That is 45% fewer houses on the shelf. Condos and townhomes went from 772 to 480. TICs went from 108 to 67. Both of those are down close to 40%. Last spring's inventory was already thin, and this spring did not deliver two thirds of it.
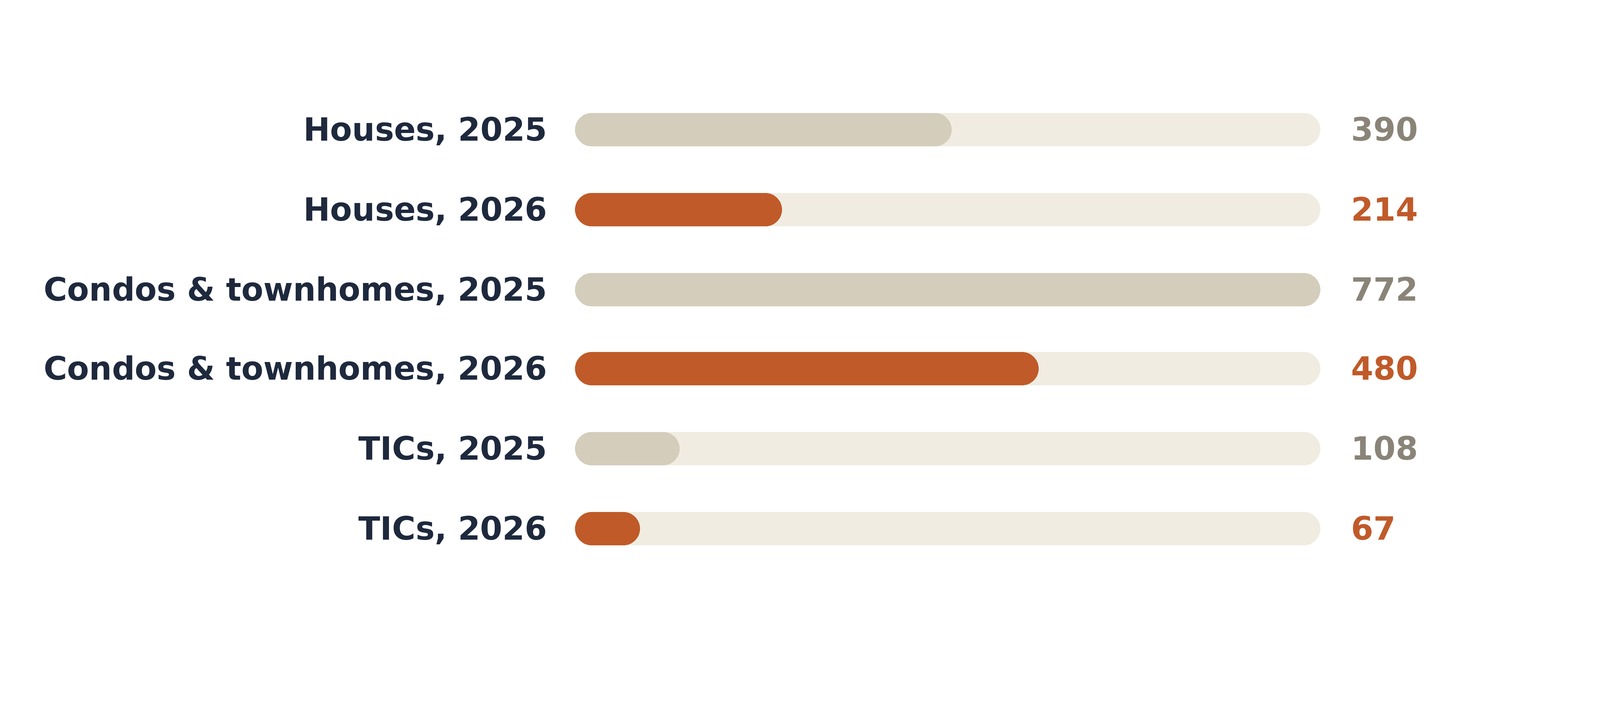
By the numbers
| Segment | Months of supply, June 2026 | A year ago | Active listings, May 2026 | A year ago |
|---|---|---|---|---|
| Houses, single-family | 0.7 | 1.8 | 214 | 390 |
| Condos and townhomes | 1.7 | 3.9 | 480 | 772 |
| Tenancy-in-common, TIC | 1.1 | 4.1 | 67 | 108 |
| Balanced market, reference | 4 to 6 | 4 to 6 |
Rates are not the story
The obvious counter-argument is rates, so let me rule it out on the record. The thirty-year mortgage is near 6.5%. Fed funds is near 3.6%. Neither has moved much across this year. Nothing about borrowing got cheaper, which means none of this can be blamed on cheap money flooding back into the market. Here is my read on the other direction. Rates near six and a half percent are one reason owners are staying put. If your loan was written in the pandemic years, selling means giving that loan up and financing the next house at today's cost, and most owners look at that trade and decline it. The lock-in is real, and it sits on the supply side of the equation, not the demand side. For anyone buying or selling this month the distinction is practical. You are not competing against a wave of cheap money. You are competing for a short shelf, and a short shelf behaves differently.
What changed
0.7 mo
months of supply for houses, a year ago 1.8
homes for sale, at a twenty-year low for the month of June
What did not
6.5%
the thirty-year mortgage, flat for most of the year
money never got cheap; the listings stopped coming to market
Where the overbids come from
Now the arc closes. A house selling 24% over asking in eleven days looks like crowd behavior if the crowd is all you watch. It is arithmetic. At 0.7 months of supply, the whole active buyer pool arrives at the same address on the same weekend, because there is no second option down the street to divide it. Price a home honestly, prepare it properly, and that entire pool shows up in one place. What comes out the other side is the overbid, the eleven-day sale, and the spillover into condos and TICs. Buyers did not lose their heads. The shelves emptied, and the bidding is what an empty shelf does.
How I would use this
Sellers first. The leverage on your side of the table is the strongest this market has produced in twenty years, and it is easy to underrate. That is not an argument for a high price. It is an argument for the honest one. Set the pricing path at the number your real comparables support, put the property in front of buyers in genuinely good condition, and let scarcity do the rest of the work. The buyer pool has nowhere else to go. It shows up for the homes that are ready and it hesitates on the ones that are not.
Buyers next, and the honest version is not comfortable. Waiting for more choice has not paid off, and nothing in this data promises that the next few months will reward it either. So prepare instead of waiting. Build the budget from what comparable homes actually closed at rather than from asking prices. Get fully underwritten before you start touring. Decide in advance what you will do when the right house appears, because a three-week market gives you days to move, not weeks. The buyers winning here are not braver than you. They finished their homework earlier. And if you own and are genuinely unsure, that is a conversation rather than a data problem. Selling into this scarcity, holding, or something between the two are each right for different owners. Sometimes the honest recommendation is to wait. Once we know what you are actually solving for, we can decide what makes sense, and that is the conversation the team is built for.
What could make me wrong
Two limits, and I would rather name them myself. The first is the metric. Months of supply drops when listings are scarce and it also drops when sales run fast, so on its own it can be read the wrong way. The listing count is what settles the question. Inventory is down about 40% on its own, and that is a shortage of homes rather than a mirage created by quick turnover. The second is scope. June is one month and these are citywide medians. Your block, your building and your price band can each run hotter or cooler than the city, and no two properties are alike. What I will stand behind is the direction, which is the same in every property type. Data deemed reliable but not guaranteed, subject to revision. General information, not legal, tax, or financial advice.
If you take one thing out of this issue, take this. The defining fact of 2026 in San Francisco is not price and it is not how buyers are behaving. It is that owners stopped listing. Until the listings come back, none of this is a mood waiting to break. It is arithmetic, and arithmetic does not get tired. The open question is the fall. Whether sellers return once the market comes back from summer is the reading I will be watching, and I will report it here either way. If you own, if you are shopping, or if you are weighing a move and have not landed anywhere, that is exactly the conversation the team is here for.
AI Corridor Scoreboard
The softest corner of the city gets one reading in every issue. These are the condos near the new AI offices, tracked here so the turn is visible while it is happening rather than afterward.
| Issue | Date | Reading | Call |
|---|---|---|---|
| #01 | Jun 7, 2026 | Soft. Only 37 to 43% of SoMa, Mission Bay, and downtown condos sold over asking. | Clearest buyer opportunity in the city. |
| #02 | Jun 10, 2026 | Turning at the edges. Citywide condos hit 101.4% of list in May; inventory fell to 584 from 905. The corridor towers remain the soft end. | Window narrowing, not closed. |
| #03 | Jun 13, 2026 | Still the bottom of the overbid table. Corridor sale-to-list at about 98 to 99% versus 103.6% citywide, trailing year. | Opportunity intact for negotiators. |
| #04 | Jun 17, 2026 | Still the soft floor while houses raced ahead. Corridor near 98 to 99% of list versus 103.8% citywide and about 123% for single-family in the last 30 days. | Buyer opportunity holds; the gap to houses only widened. |
| #05 | Jun 21, 2026 | Cash, not heat. Corridor condos carry heavier cash than the citywide condo average, about 42% versus 37%, yet still sell near 98.7% of list with only about 20% over asking versus 45% citywide. Cash concentrates here; competition does not. | Negotiating room for financed buyers. |
| #06 | Jun 25, 2026 | Still the calm corner while the house middle runs hot. District 9 condos, SoMa, Mission Bay, and South Beach, sold right at list, about 100%, with only 35% over asking on 300 sales, against the $1.5M to $3M house band at 122 to 125% of list. | Buyer opportunity holds where the bidding wars are not. |
| #08 | Jul 5, 2026 | Still the soft floor even as the top books records. District 9 condos, SoMa, Mission Bay, and South Beach, sold near 100% of list with heavy cash and light competition, while $5M+ houses set a decade volume record at about 112% of list on roughly 64% cash. Cash without a crowd here. | Buyer opportunity intact where the crowds are not. |
| #09 | Jul 10, 2026 | Still the soft floor at the halfway mark. District 9 condos, SoMa, Mission Bay, and South Beach, sold near 100% of list with only about 36% over asking on roughly 290 sales this year, while citywide houses ran near 121% of list. The widest lane in the city stays open. | Clearest buyer opportunity holds into the second half. |
| #10 | Jul 14, 2026 | Still soft while the headline is elsewhere. June's million-over-asking story is a west-side and central house market, not the AI-corridor towers. District 9 condos, SoMa, Mission Bay and South Beach, ran about 10% below last year even as volume climbed. Activity returns to the corridor; pricing has not. | Still the clearest buyer opening in the city. |
| #11 | Jul 17, 2026 | Unmoved by the house story. While overbidding ran one tier below the trophy core, the corridor and condo core cleared near asking, and the two flat lanes the field named as spillover candidates, Hayes Valley and Lower Pacific Heights, stayed calm in closed data. | Still the clearest buyer opening in the city. |
| #12 | Jul 21, 2026 | Still the calm corner, and it proves the point. District 9 condos, SoMa, Mission Bay, and South Beach, sold right at list, about 100%, with only 31% over asking on 836 sales, while mid-priced houses cleared 123 to 127% of list. Condos rarely get listed low to start a war, so the overbid never appears. | Buyer leverage holds where the list-low tactic is not used. |
| #13 | Jul 25, 2026 | Graduated to the essay. Back at asking for the first time since 2022, after three springs about 1% below it, and the clock changed: median market time fell from 38 days to 19 and the share selling over asking roughly doubled, from the low twenties to the mid forties. Price at par, speed doubled. | Negotiating room intact; the window now narrows in speed, not price. |
| #14 (this issue) | Jul 29, 2026 | Read on supply this time, not price. Citywide condo and townhome months of supply fell from 3.9 to 1.7 in a year and active listings from 772 to 480, so even the calmest lane in the city now offers less to choose from. This issue did not re-measure corridor pricing. | Buyer opening holds on price; the shelf behind it is thinner. |
- Houses hit 0.7 months of supply in June. That is roughly three weeks of homes on the shelf and the weakest June supply in at least twenty years of this series. Even the peak spring markets of 2021 and 2022 held 1.6 months. Four to six months is what balanced looks like, for reference.
- Every lane is dry, not only houses. Condos and townhomes fell to 1.7 months, TICs to 1.1, and the citywide condo figure lost more than half its cushion in a year. Active listings are down roughly 40% across all property types, and that is what separates a real shortage from sales that are simply closing fast.
- Rates do not explain it. The thirty-year mortgage has held near 6.5% all year and fed funds near 3.6%, so borrowing never got cheap. My read is that rates are working on the other side of the ledger: an owner carrying a pandemic-era loan has to trade it for one near six and a half percent, and most of them stay put instead.
- So the bidding is arithmetic rather than mania. With three weeks of inventory citywide, one well-priced and well-prepared home collects the entire active buyer pool in a single weekend, since there is no alternative a block away to divide it. Overbids, short days on market and the spillover into condos and TICs all follow from that.
- Sellers hold the strongest position this market has produced in twenty years, so the move is an honest pricing path and letting scarcity work, not reaching for a number. Buyers have not been rewarded for waiting, so get underwritten and be ready to decide quickly. If you are undecided, waiting is still a legitimate recommendation.
All of these lanes sit inside the market explorer. Change the property type there and pull the supply picture for the blocks you care about, whether that is Noe Valley, Glen Park or your own street.
Sources and further reading
- Freddie Mac Primary Mortgage Market Survey, the weekly mortgage rate benchmark
- Selling in San Francisco, starting with whether you should
- How we help buyers
- Issue #13: The Pressure Valve, where the pressure went
Methodology and sources
Source: POTM Command governed MLS analytics, refreshed July 26, 2026. Months of supply and active-listing series are computed monthly for San Francisco County, single-family, condominium and townhome, and tenancy-in-common segments, back to January 2005. Months of supply is active inventory divided by the trailing monthly sales pace. June 2026 is the latest complete month for supply; active-listing comparisons use May, the latest complete month in that series. Two things keep this honest. First, a low months-of-supply figure can reflect scarce listings or simply fast sales, so the independent active-listing count matters: listings are down about 40% on their own, which confirms a supply shortage rather than a mirage of quick turnover. Second, June is a single month and these are citywide medians, so any block or building can run hotter or cooler. The direction is the same across every property type. Rate figures are from FRED: thirty-year fixed mortgage (MORTGAGE30US) and federal funds rate (FEDFUNDS), latest observations late July 2026. Data deemed reliable but not guaranteed, subject to change, correction, and revision. General information, not legal, tax, or financial advice.
Level Up Market Intel
What does this mean for your home, or the one you want?
The page above is the data and the context. What it means for one address, one budget and one timeline is a conversation. David reads this market every day.