Market Notes, Issue #20, August 25, 2026
The HOA Line
Houses are hot and condos are not. Every report this year has landed there, and it is accurate and nearly worthless at the same time, because there is no single condo market. There are two of them. What divides them is not the neighborhood, not the vintage of the building and not parking. It is the monthly HOA dues.
By David Juarez, Level Up Group · Compass · Published August 25, 2026
Data source POTM, governed SFAR MLS data
You have read the same headline in every market report this year. Houses hot, condos not.
The headline is accurate. Across the last six months the median San Francisco house sold at +22.5% over asking and the median condo at +1.3%, on 1,276 house sales and 1,375 condo sales. That is not a narrow gap.
It is also nearly useless the moment you have to act on it. Condos are not one market that happens to be flat. They are two markets, and the boundary between them is not the neighborhood, not the year on the building and not a parking space. It is the dues bill every month.
One number does all the sorting
Here is the test. Line up every condo that closed in the city over the last six months, split them into three groups by their monthly homeowners association dues, then put a single question to each group. How many of those sales beat the asking price by 10% or more?
Dues under $500 a month: 59.9% of sales. Dues from $500 to $1,000: 26.0%. Dues above $1,000: 11.1%. Each step up the ladder cuts the share close to half. Three sales in five end in a double-digit overbid under $500, at a median 13 days. Above $1,000 it is one in nine.
Turn the distribution around and the message holds. Among sales with dues over $1,000, the most common single outcome is a close below asking, at 39.9%, against 38.9% above asking and 21.2% exactly at it, on a median 19 days. Past that point on the dues sheet, negotiating the price down is not a special case. It is the normal one.
An obvious objection: I picked those brackets. So test them. Redraw the cuts at $800 and $1,200 instead of $500 and $1,000 and nothing reorders. More dues still means fewer bidding wars, and the calendar still stretches from 13 days at the low end to roughly three weeks at the high end. The relationship underneath is continuous, and a bracket is only a slice of it, which is why the By the numbers table below carries all four. When a finding survives every way of slicing, the finding is doing the work and the slicing is incidental.
One more thing, and I will keep it to what the data supports. You might expect high-dues buildings to trade at a visible discount per square foot. They do not, or at least not clearly: the figure lands near the low-dues group at both ends of the range. The buildings and the neighborhoods being compared are not alike, which makes that a rough comparison. Call it suggestive, not proven.
How this reads on the map
Two things you have probably been told are both true, and both come back to dues. First, older buildings do better: pre-1940 condos ran +10.7% over asking across these six months, while anything built in 2015 or later closed at asking. Second, certain neighborhoods are stronger. That one holds because neighborhoods sort themselves by building type. The flats cut out of Victorians and Edwardians sit in the house districts. The towers sit downtown and along the waterfront.
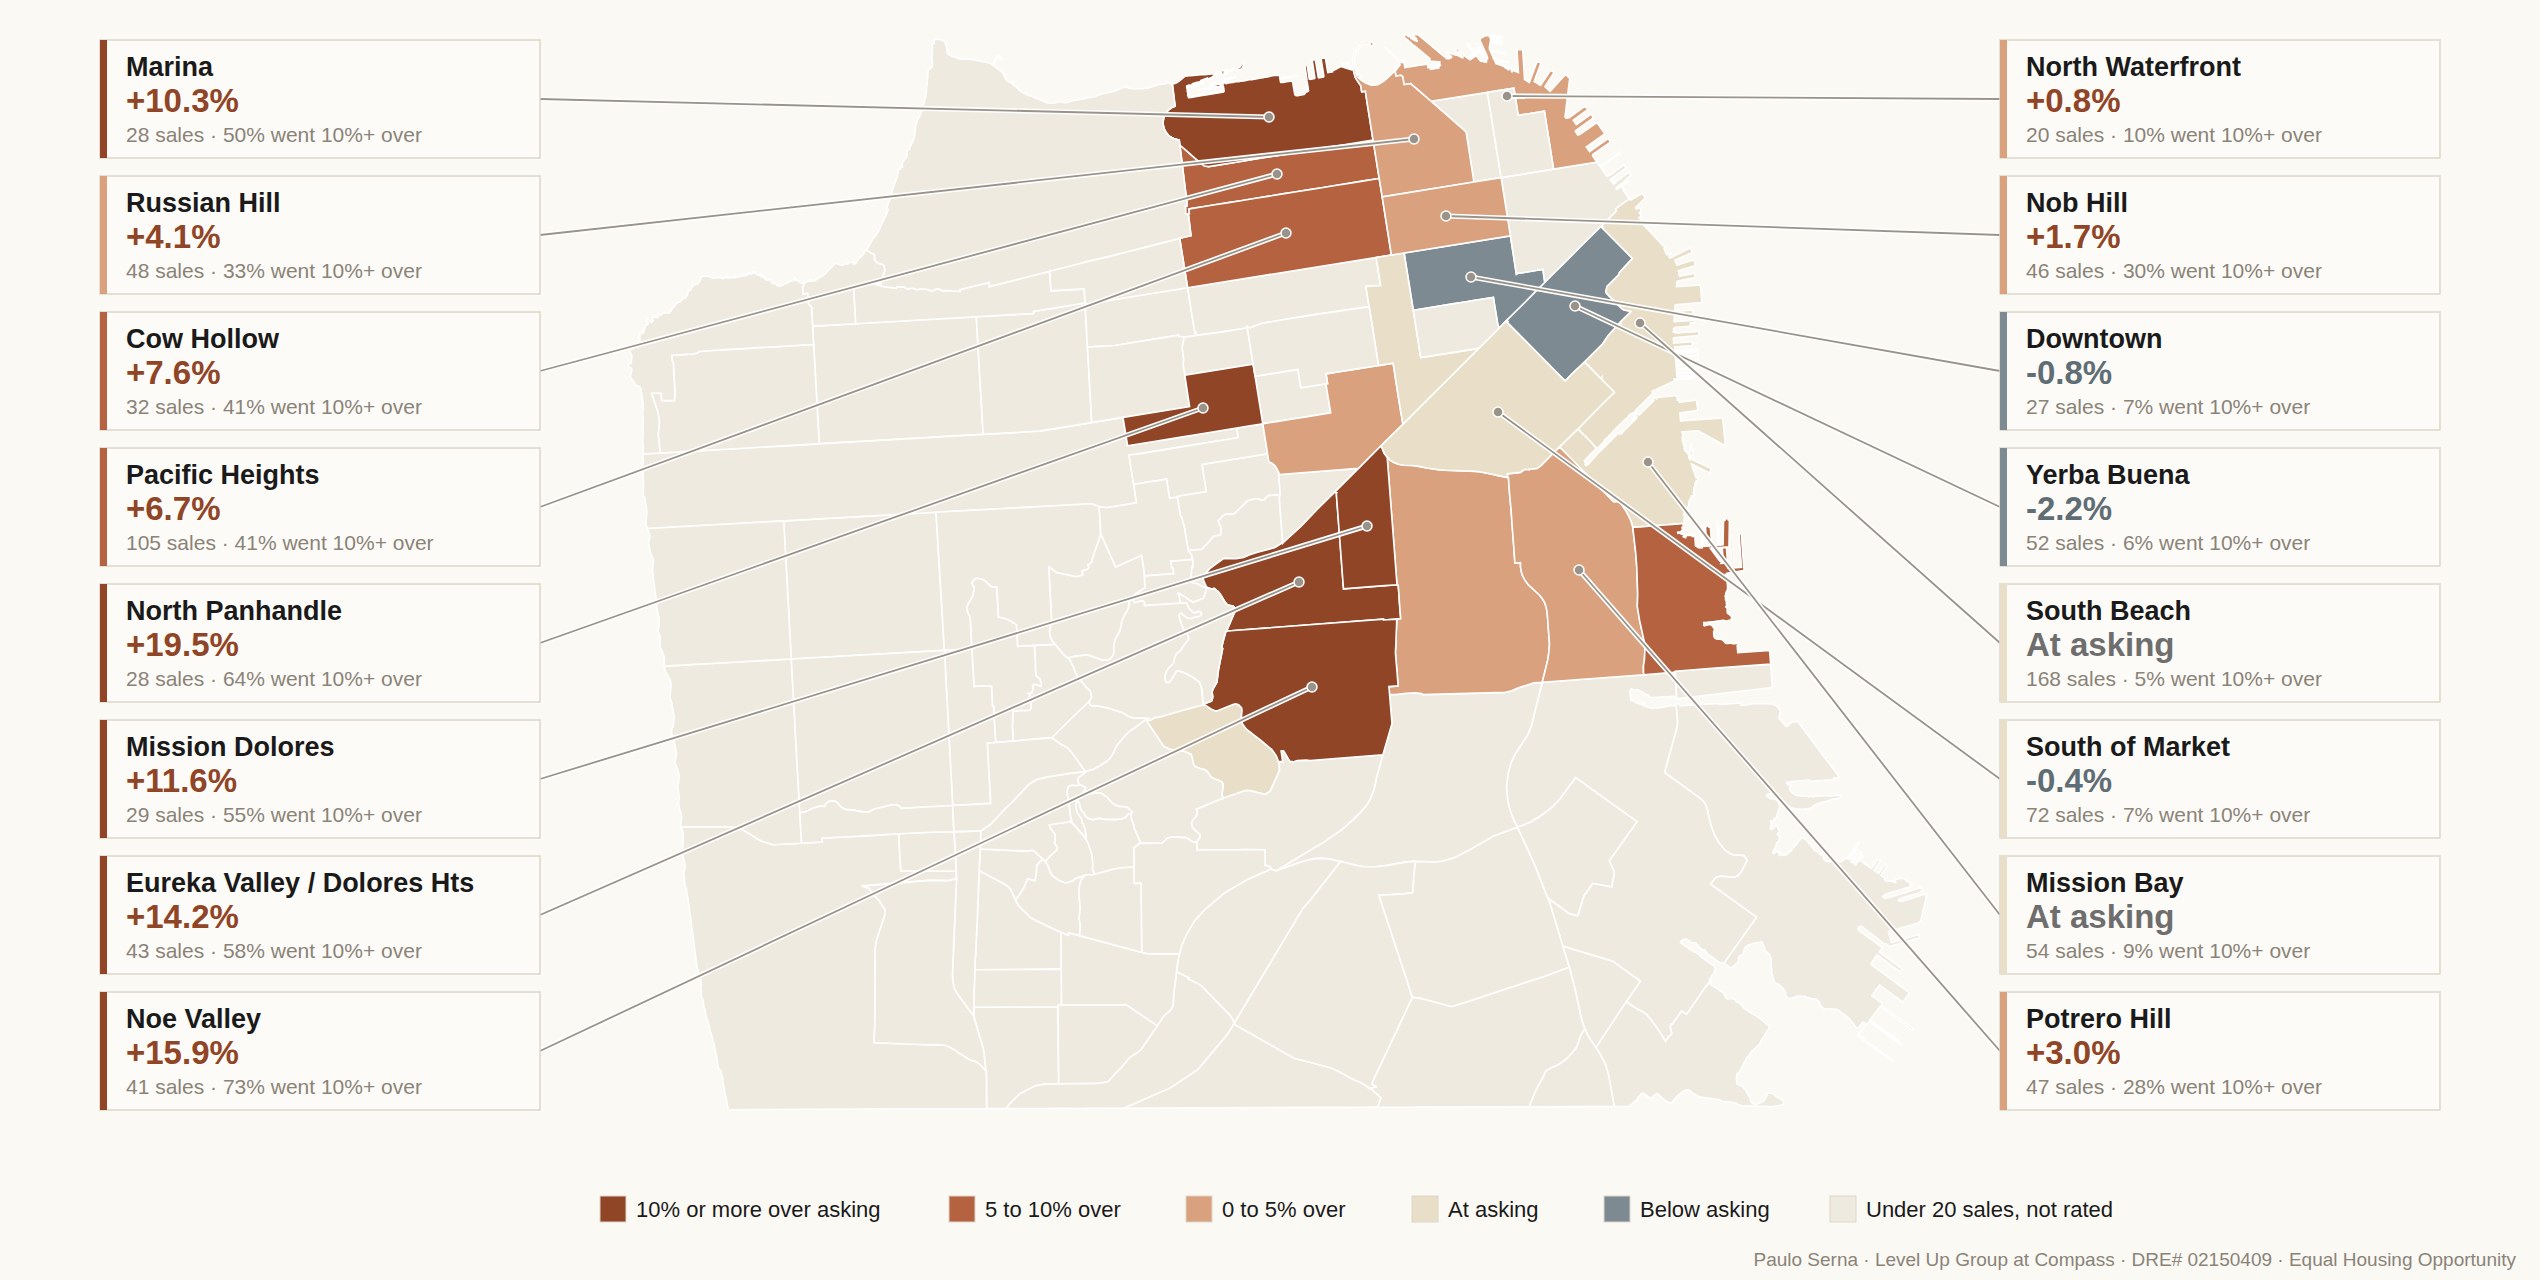
At the top of the map: North Panhandle at +19.5% over asking, Noe Valley +15.9%, Eureka Valley +14.2%, Mission Dolores +11.6%. Noe Valley also cleared asking on 92.7% of its condo sales, the best share of any neighborhood with 20 or more of them. At the bottom: Yerba Buena, Downtown and SoMa below asking, with South Beach, Mission Bay and Van Ness right at it, and that corridor needs a month or more to sell. It is the same corridor where Issue #19 found cash buyers negotiating genuine discounts. Weight matters here too. South Beach alone contributes 168 sales, as many as the five strongest neighborhoods put together, which goes a long way toward explaining the citywide condo figure. The Marina has stopped sitting in between, at +10.3% over asking these six months, with Pacific Heights at +6.7%, and it is the pre-war flat side of those mixed streets doing the work. Take the 1 and 2 bedroom condos across Marina, Pacific Heights and Cow Hollow and 40.4% of sales cleared asking by double digits, at a median 9 days. Cole Valley, Corona Heights, Inner Richmond and Bernal Heights are running hot as well, but on fewer than 20 sales apiece this half, so the map leaves them unrated.
Every one of those angles describes a single mechanism. A flat carved out of a 1926 four-unit Victorian carries almost nothing in dues, because there is no elevator, no lobby, no doorman and no gym to pay for. A 2015 tower carries $1,200 a month, permanently, and that figure rises. Anyone shopping on a fixed monthly budget feels it immediately, since dues leave the same pocket as the mortgage payment and lenders treat them the same way, which the CFPB's plain-language explainer sets out. So the low-dues building is not merely cheaper to own. Its buyer pool is materially larger, and a larger pool is what produces a bidding war.
Two sales that ignored their bracket
Two homes from this cycle, both sitting in the middle of the dues range, the $500 to $800 group. That bracket has a median sale closing just above asking and roughly three in ten clearing double digits. Neither one behaved like a middle-bracket sale.
7 Casa Way, Unit 1, in the Marina. One bedroom, one bath, a 1926 building, dues of $626. It listed at $929,000 and closed on August 19 at $1,260,000, or +35.6% over asking, in 12 days. The building has done this before: Unit 5 sold at $1,600,000 against a $1,195,000 ask in July 2024, also inside 12 days.
1945 Washington Street, Unit 204, in Pacific Heights. Two bedrooms, two baths, parking, dues around $797, listed at $1,095,000. It pulled 12 offers and went into contract above $1.4M. The sale was still pending when this issue went out, so the exact number is not on the record yet and I will update it once it records. Look at the year on the building though: 1987. That is not a pre-war conversion.
Here is where I want to be careful, because two sales are easy to misuse. Neither of these proves that low dues win. They prove close to the reverse: two homes from the ordinary middle of the dues range went straight through what their bracket predicted, and one of them sits in a 1987 building. What a bracket gives you is odds, nothing more. In the $500 to $800 group, about three sales in ten clear double digits over asking, and both of these landed in that three. My read is that a buyer who has absorbed the flat-condo headline and offers accordingly on a home like either of these does not lose narrowly.
What the strong ones share
Getting into the running is what low dues do. Winning comes down to a different question: does this live like a home, or like a room with a view?
That means genuine square footage rather than a clever plan. Light coming in from more than one side. A second bedroom an adult can sleep in. Outdoor space, or a view that does not depend on what a neighbor does with a roofline. Parking counts too, though less than the folklore claims: units with it cleared double digits over asking 30.6% of the time against 23.3% without.
Run it by bedroom count and the pattern is monotone. Three bedrooms cleared double digits 48.2% of the time, in a median 13 days. Two bedrooms, 31.5% and 14 days. One bedrooms, 13.0% and 22 days. Studios: 26 median days and, out of 45 sales, zero double-digit overbids. A condo behaves like a house in proportion to how much it works like one.
My read
If a condo is on your list, pull the dues before the kitchen wins you over.
This is not an argument that high dues are a bad deal. The elevator, the front desk and the roof deck are sometimes exactly what a person wants, and that building comes with a calmer purchase and room to negotiate on price. Valued honestly, that is a genuine advantage.
Pull them because the number tells you which negotiation is waiting on the other side of the door. Under $500 a month, plan for competition and be ready to act. Over $1,200, plan on having time and actually use it. The error I see repeatedly is one plan carried into both rooms. A buyer absorbs the flat-condo headline, offers near asking on the best low-dues flat they have seen all year, and loses it to someone who read the room correctly. The next comparable listing arrives four months later at a higher price.
Sellers in a high-dues building have one number to get out in front of. Two things beat another week of staging here: a reserve study that is current and clean, which California law requires at least every three years, and a plain explanation of where that money actually goes each month.
By the numbers
| Monthly HOA dues | Sales | Median vs asking | Median days on market | Went 10%+ over | Median $ per sq ft |
|---|---|---|---|---|---|
| Under $500 | 302 | +13.0% | 13 | 59.9% | $1,184 |
| $500 to $800 | 335 | +1.8% | 16 | 31.0% | $1,021 |
| $800 to $1,200 | 342 | At asking | 20 | 17.3% | $1,003 |
| $1,200 and up | 342 | At asking | 18 | 9.1% | $1,187 |
AI Corridor Scoreboard
The softest corner of the city gets one reading in every issue. These are the condos near the new AI offices, tracked here so the turn is visible while it is happening rather than afterward.
| Issue | Date | Reading | Call |
|---|---|---|---|
| #20 (this issue) | Aug 25, 2026 | Two markets, one label. Corridor towers still at or below asking over the past six months (South Beach at asking on 168 sales, Yerba Buena -2.2%) while low-dues flats citywide cleared 10%+ over in 59.9% of sales. | Check the dues before you plan the offer. |
| #19 | Aug 18, 2026 | Where cash buys the most and shouts the least. Corridor condos ran 41.7% cash in the past 12 months, the heaviest concentration this series tracks, yet cash and financed closed at the same price, 99.2% versus 99.3% of asking. Cash's whole edge here is the clock: 20 median days on market against 39 financed. | Financed buyers give up nothing on price here; they pay in patience. |
Show the 16 earlier readings
| Issue | Date | Reading | Call |
|---|---|---|---|
| #17 | Aug 9, 2026 | Zero, which is the cleanest reading this scoreboard has produced. Across 368 corridor condo closings so far in 2026, not one sold $1,000,000 over asking, and the typical one closed slightly under asking: South Beach 0.7% below on 183 sales, South of Market 1.0% below on 79, Yerba Buena 2.4% below on 53, Mission Bay exactly at asking on 53. In an issue about where the overbidding is, the corridor is where it is not. | Buyer opening holds, and this issue measures exactly how wide it is. |
| #16 | Aug 6, 2026 | Flat in every window, which this issue argues is the whole point. South Beach condos read 100.0% of asking at 30, 90 and 180 days and 99.0% over the trailing year. South of Market reads 99.4, 99.8, 99.6 and 99.0. Four windows, one answer. Every house lane in this issue moved when the window moved; the corridor did not, and a segment that reads the same no matter how you slice it is a segment that is not turning. | Buyer opening holds, and now it is measured four ways instead of one. |
| #15 | Aug 2, 2026 | Unchanged at the bottom of the same ladder. This issue extended the over-asking gradient into small multifamily, and the corridor still anchors the low end: right at asking, while two-unit buildings cleared 11.7% over and houses 23.8%. The ordering is by how much a property lives like a house, and a corridor tower is the furthest thing from one. | Buyer opening holds, and this issue explains why it persists. |
| #14 | Jul 29, 2026 | Read on supply this time, not price. Citywide condo and townhome months of supply fell from 3.9 to 1.7 in a year and active listings from 772 to 480, so even the calmest lane in the city now offers less to choose from. This issue did not re-measure corridor pricing. | Buyer opening holds on price; the shelf behind it is thinner. |
| #13 | Jul 25, 2026 | Graduated to the essay. Back at asking for the first time since 2022, after three springs about 1% below it, and the clock changed: median market time fell from 38 days to 19 and the share selling over asking roughly doubled, from the low twenties to the mid forties. Price at par, speed doubled. | Negotiating room intact; the window now narrows in speed, not price. |
| #12 | Jul 21, 2026 | Still the calm corner, and it proves the point. District 9 condos, SoMa, Mission Bay, and South Beach, sold right at list, about 100%, with only 31% over asking on 836 sales, while mid-priced houses cleared 123 to 127% of list. Condos rarely get listed low to start a war, so the overbid never appears. | Buyer leverage holds where the list-low tactic is not used. |
| #11 | Jul 17, 2026 | Unmoved by the house story. While overbidding ran one tier below the trophy core, the corridor and condo core cleared near asking, and the two flat lanes the field named as spillover candidates, Hayes Valley and Lower Pacific Heights, stayed calm in closed data. | Still the clearest buyer opening in the city. |
| #10 | Jul 14, 2026 | Still soft while the headline is elsewhere. June's million-over-asking story is a west-side and central house market, not the AI-corridor towers. District 9 condos, SoMa, Mission Bay and South Beach, ran about 10% below last year even as volume climbed. Activity returns to the corridor; pricing has not. | Still the clearest buyer opening in the city. |
| #09 | Jul 10, 2026 | Still the soft floor at the halfway mark. District 9 condos, SoMa, Mission Bay, and South Beach, sold near 100% of list with only about 36% over asking on roughly 290 sales this year, while citywide houses ran near 121% of list. The widest lane in the city stays open. | Clearest buyer opportunity holds into the second half. |
| #08 | Jul 5, 2026 | Still the soft floor even as the top books records. District 9 condos, SoMa, Mission Bay, and South Beach, sold near 100% of list with heavy cash and light competition, while $5M+ houses set a decade volume record at about 112% of list on roughly 64% cash. Cash without a crowd here. | Buyer opportunity intact where the crowds are not. |
| #06 | Jun 25, 2026 | Still the calm corner while the house middle runs hot. District 9 condos, SoMa, Mission Bay, and South Beach, sold right at list, about 100%, with only 35% over asking on 300 sales, against the $1.5M to $3M house band at 122 to 125% of list. | Buyer opportunity holds where the bidding wars are not. |
| #05 | Jun 21, 2026 | Cash, not heat. Corridor condos carry heavier cash than the citywide condo average, about 42% versus 37%, yet still sell near 98.7% of list with only about 20% over asking versus 45% citywide. Cash concentrates here; competition does not. | Negotiating room for financed buyers. |
| #04 | Jun 17, 2026 | Still the soft floor while houses raced ahead. Corridor near 98 to 99% of list versus 103.8% citywide and about 123% for single-family in the last 30 days. | Buyer opportunity holds; the gap to houses only widened. |
| #03 | Jun 13, 2026 | Still the bottom of the overbid table. Corridor sale-to-list at about 98 to 99% versus 103.6% citywide, trailing year. | Opportunity intact for negotiators. |
| #02 | Jun 10, 2026 | Turning at the edges. Citywide condos hit 101.4% of list in May; inventory fell to 584 from 905. The corridor towers remain the soft end. | Window narrowing, not closed. |
| #01 | Jun 7, 2026 | Soft. Only 37 to 43% of SoMa, Mission Bay, and downtown condos sold over asking. | Clearest buyer opportunity in the city. |
- No gradient in the condo market is cleaner than the dues ladder. Sales clearing 10% or more over asking: 59.9% where dues run under $500 a month, 26.0% from $500 to $1,000, 11.1% above $1,000. Move the bracket lines wherever you like and that order holds.
- The script inverts above $1,000 a month, where the most common outcome is a close below asking, 39.9% of sales, on a median 19 days. Under $500 the market runs in 13 days and three of every five sales finish in a double-digit overbid.
- Most of the older explanations reduce to this one. Pre-1940 condos outperform 2015-and-newer, and house-district flats outperform tower districts, mainly because a Victorian conversion carries next to no dues while a tower carries $1,200 a month, permanently, and climbing.
- A bracket sets odds, not outcomes. Out of the middle dues bracket, where the median sale closes just above asking, a 1926 Marina one bedroom went 35.6% over in 12 days and a 1987 Pacific Heights two bedroom collected 12 offers. Low dues put a home in the running. Whether it lives like a home decides the bidding.
Sale-to-list, market time and inventory sit in the market explorer for every San Francisco neighborhood, each carrying its reliability label. Get the dues for the building you are considering, then read its subdistrict there before you write an offer.
Methodology and sources
Source: POTM Command, governed MLS analytics, closed sales through August 21, 2026. Condo figures cover 1,375 closed condo and townhouse sales over the trailing six months, of which 1,321 reported HOA dues; the citywide house and condo comparison uses the same six months, 1,276 houses and 1,375 condos. Every figure is an exact median, never an average and never an approximation. Dues brackets are cuts of a continuous relationship, not categories; the ladder holds under any bracketing, which is why the shares lead this issue rather than the medians. Neighborhood figures use the same six months and are rated only at 20 or more sales; Cole Valley, Corona Heights, Inner Richmond and Bernal Heights fell under that floor this half and are shown unrated on the map. 1945 Washington Street was in contract and had not recorded as of publication; its figure is described in general terms and will be updated when it records. Everything here is observed, not causal. Updated August 25, 2026: every figure refreshed from the launch twelve-month window to the trailing six months.
Level Up Market Intel
What does this mean for your home, or the one you want?
The page above is the data and the context. What it means for one address, one budget and one timeline is a conversation. David reads this market every day.