Market Notes, Issue #21, August 30, 2026
The TIC Turn
Most market coverage stops at houses and condos. There is a third product in San Francisco, the tenancy in common flat, and this issue looks at it plainly. What a TIC is, what it costs to carry each month, which districts have turned competitive, and why the old warnings about it, cash only and hard to sell, no longer match what the sales show.
By Sophia Yapp, Level Up Group · Compass · Published August 30, 2026
Data source POTM, governed SFAR MLS data
Buyers here are usually handed a two-product story, houses or condos, and taught to walk past anything else. The third product is the one I want to talk about. Over the last six months it has quietly been outrunning the condo market.
Start with what it is, because the name confuses people. A tenancy in common is a share of an entire building rather than a separately deeded unit. You and your neighbors each own a percentage of the property, and a written agreement gives you the exclusive right to live in your own flat. That structure is how thousands of Victorian and Edwardian buildings in this city became homes an ordinary buyer could afford. It also arrived carrying a lot of folklore. Hard to finance. Hard to resell. The thing you settle for when the condo is out of reach. Some of that was fair once. Most of it no longer holds up against the current data, and I would rather show you than argue about it.
What turned
A year ago none of this would have been worth writing about. In the six months ending August 2025, the median TIC sale closed at asking, and it took a median 37 days to get there. Just 13.6% of sales cleared asking by 10% or more.
The last six months look different. The median sale ran +5.8% over asking at a median 16 days, and 39.8% of sales cleared asking by double digits. That double-digit share nearly tripled in a year, and it now sits ahead of condos, which came in at 29.6% clearing 10% or more. Volume held steady at the same time, 176 sales against 169 the year before, so this reads as one market changing speed rather than a new one appearing.
The TIC move is larger on every measure. Market time cut by more than half. The over-asking share up 21 points. The median price climbing from $1,000,000 to $1,205,000. Condos warmed this year too, which Issue #20 covered, but not like this.
Ten years of context
One strong year can be a bounce, so I would not stop here. The team ran the same measures back to 2016 and held every year to the same window, January 1 through August 29, so no season gets an edge. What comes out, and the full table is in By the numbers, reads like four acts.
The first act, 2016 to 2019, shows a niche that competed. A few points over asking, roughly a month on the market, and 2018 the best of them at +5.6%, with 38.5% of sales clearing double digits. Then a chapter that fits nowhere. Sales stalled in 2020. In 2021 volume hit the decade high, 294 closings by late August, while the pace fell to its slowest, 45 days, and pricing went nowhere. People bought a great many TICs that year without bidding for a single one. After that, four flat years. From 2022 through 2025 the median sale landed exactly on the asking price every time. The low point was 2023, when 2.2% of sales cleared asking by 10% or more.
Now hold 2026 up against all of that. Two of the numbers are echoes. The over-asking share, 61.2% year to date, is back at 2016-2018 levels. The double-digit share, 34.2%, is second only to 2018. The speed echoes nothing. 18 median days, in a decade where no year broke 29. Median price and price per square foot, $1,178,000 and $978 year to date, are both decade highs, and the old 2018 peak never got past $899 a foot. Put plainly, this year is running 2018's level of competition at twice 2018's speed and at prices no year has matched. My read is that this is not a market returning to an old normal. Nothing in the last ten years looks like 2026.
One note so two figures do not look like they contradict each other. The decade table runs January to August, and on that basis 2026 sits at +2.9% over asking. Everywhere else this issue quotes the trailing six months, which is +5.8%. Both are accurate. The year-to-date version simply carries the cooler January and February with it.
What you are actually buying
Two numbers define the product. It trades at a median $986 per square foot against $1,101 for condos, a 10.4% discount on a home of much the same size, and its median reported dues are $450 a month against $823, because a small self-managed building has no tower payroll to fund. The rest of the profile is age and size. The typical TIC on the market in 2026 sits in a building that went up in 1909, where the typical condo building dates to 1989. Median size is about 1,200 square feet, essentially the median condo.
That profile should sound familiar. The hottest corner of the attached-home market in Issue #20 was the low-dues flat in an older building, and a TIC is exactly that, only with a different legal structure holding it up. Once you notice the overlap, this turn stops being a surprise.
Checking the folklore
The loudest claim is that TICs are cash only. Over the last six months, among TIC sales with reported financing, 24.7% were cash. Condos in the same window ran 37.0% cash. Half of TIC sales closed with a conventional loan. That is worth sitting with. The product people call unfinanceable had the lower cash share of the two. Fractional TIC financing is an established market now. The rates and terms are genuinely different from condo loans, and that is a conversation for a lender who works in TICs regularly. It is a question to ask early, not a reason to skip the open house.
The second claim is that the format is dying out. Every year since 2016, setting aside the everything-spike of 2021, the city has closed somewhere between 232 and 326 TIC sales, and this year is pacing near the top of that band. Holding a steady tenth of the flat market for a decade is neither a fad nor a fade. It is a lane.
Where the heat is, and one open question
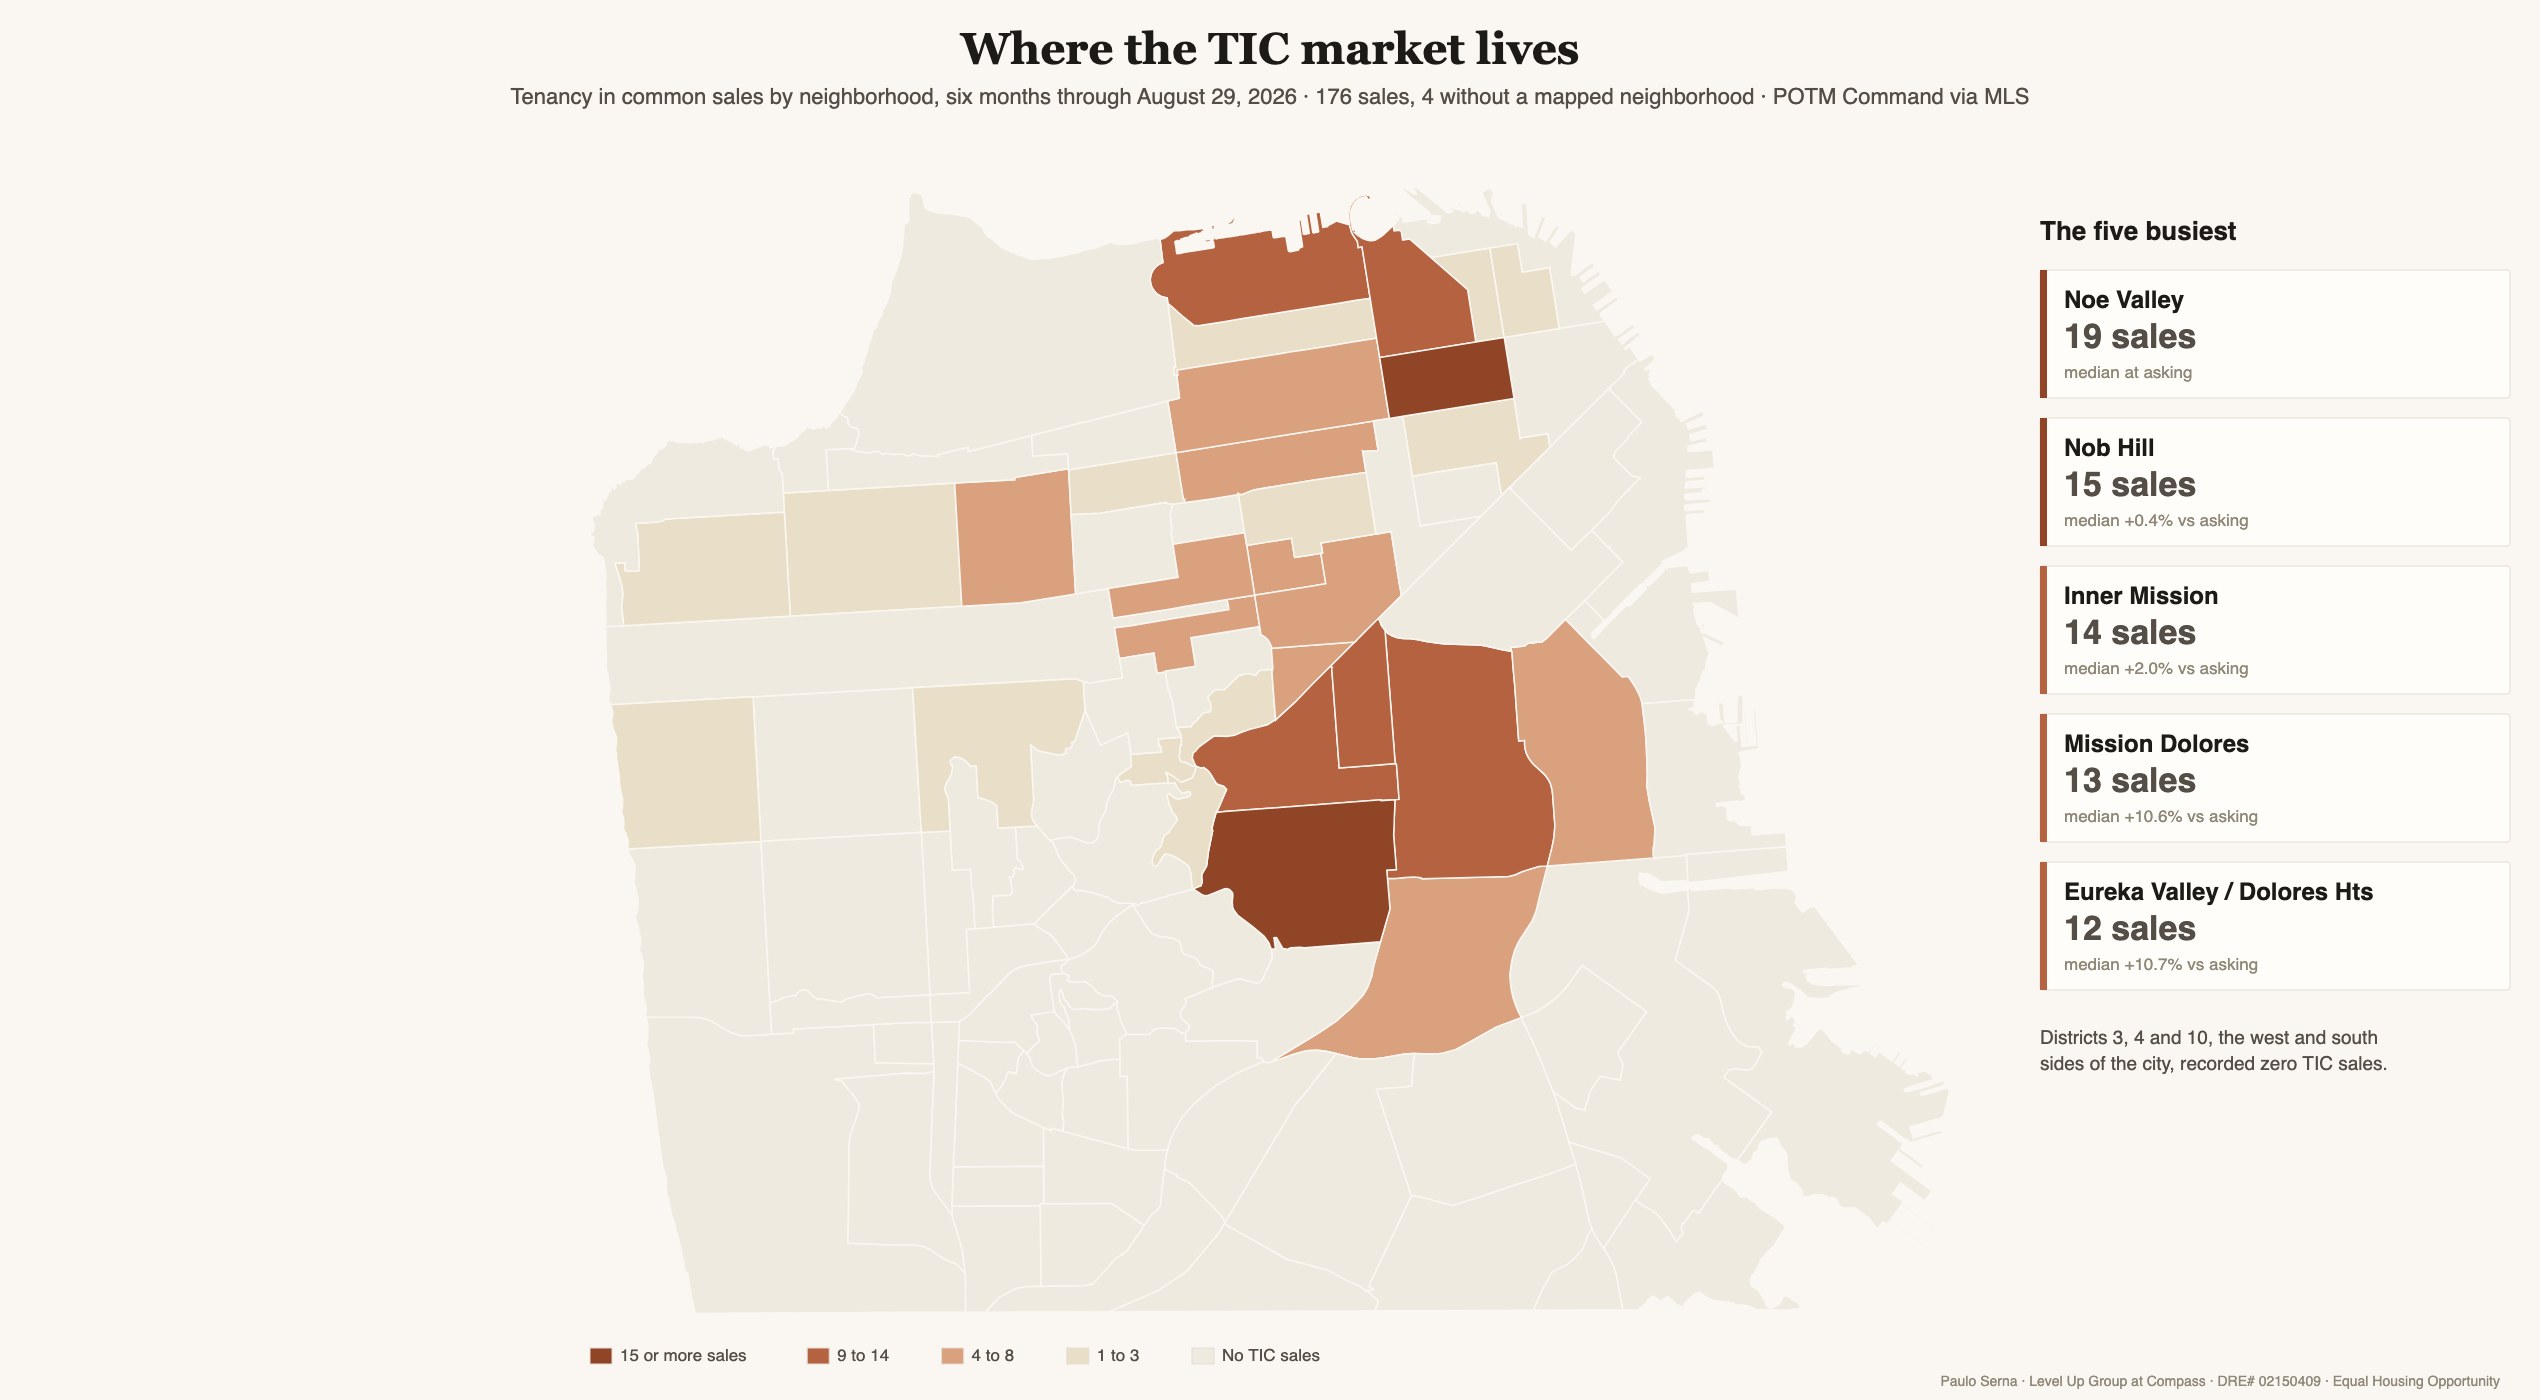
Start with where TICs are not. Districts 3, 4 and 10 recorded no TIC sales in this window at all, which follows from a housing stock built as single-family houses. Everything else concentrates on the north side, and it does not trace the condo map. District 6 was strongest at +12.0% over asking, with 80% of its sales clearing. The Richmond, District 1, came in at +12.7%, though on a sample small enough to be labeled Directional. District 7, the Marina and Pacific Heights, ran +11.9%, and the Marina on its own reached +17.8% on 9 sales, Directional again. Mission Dolores managed +10.6% on 13.
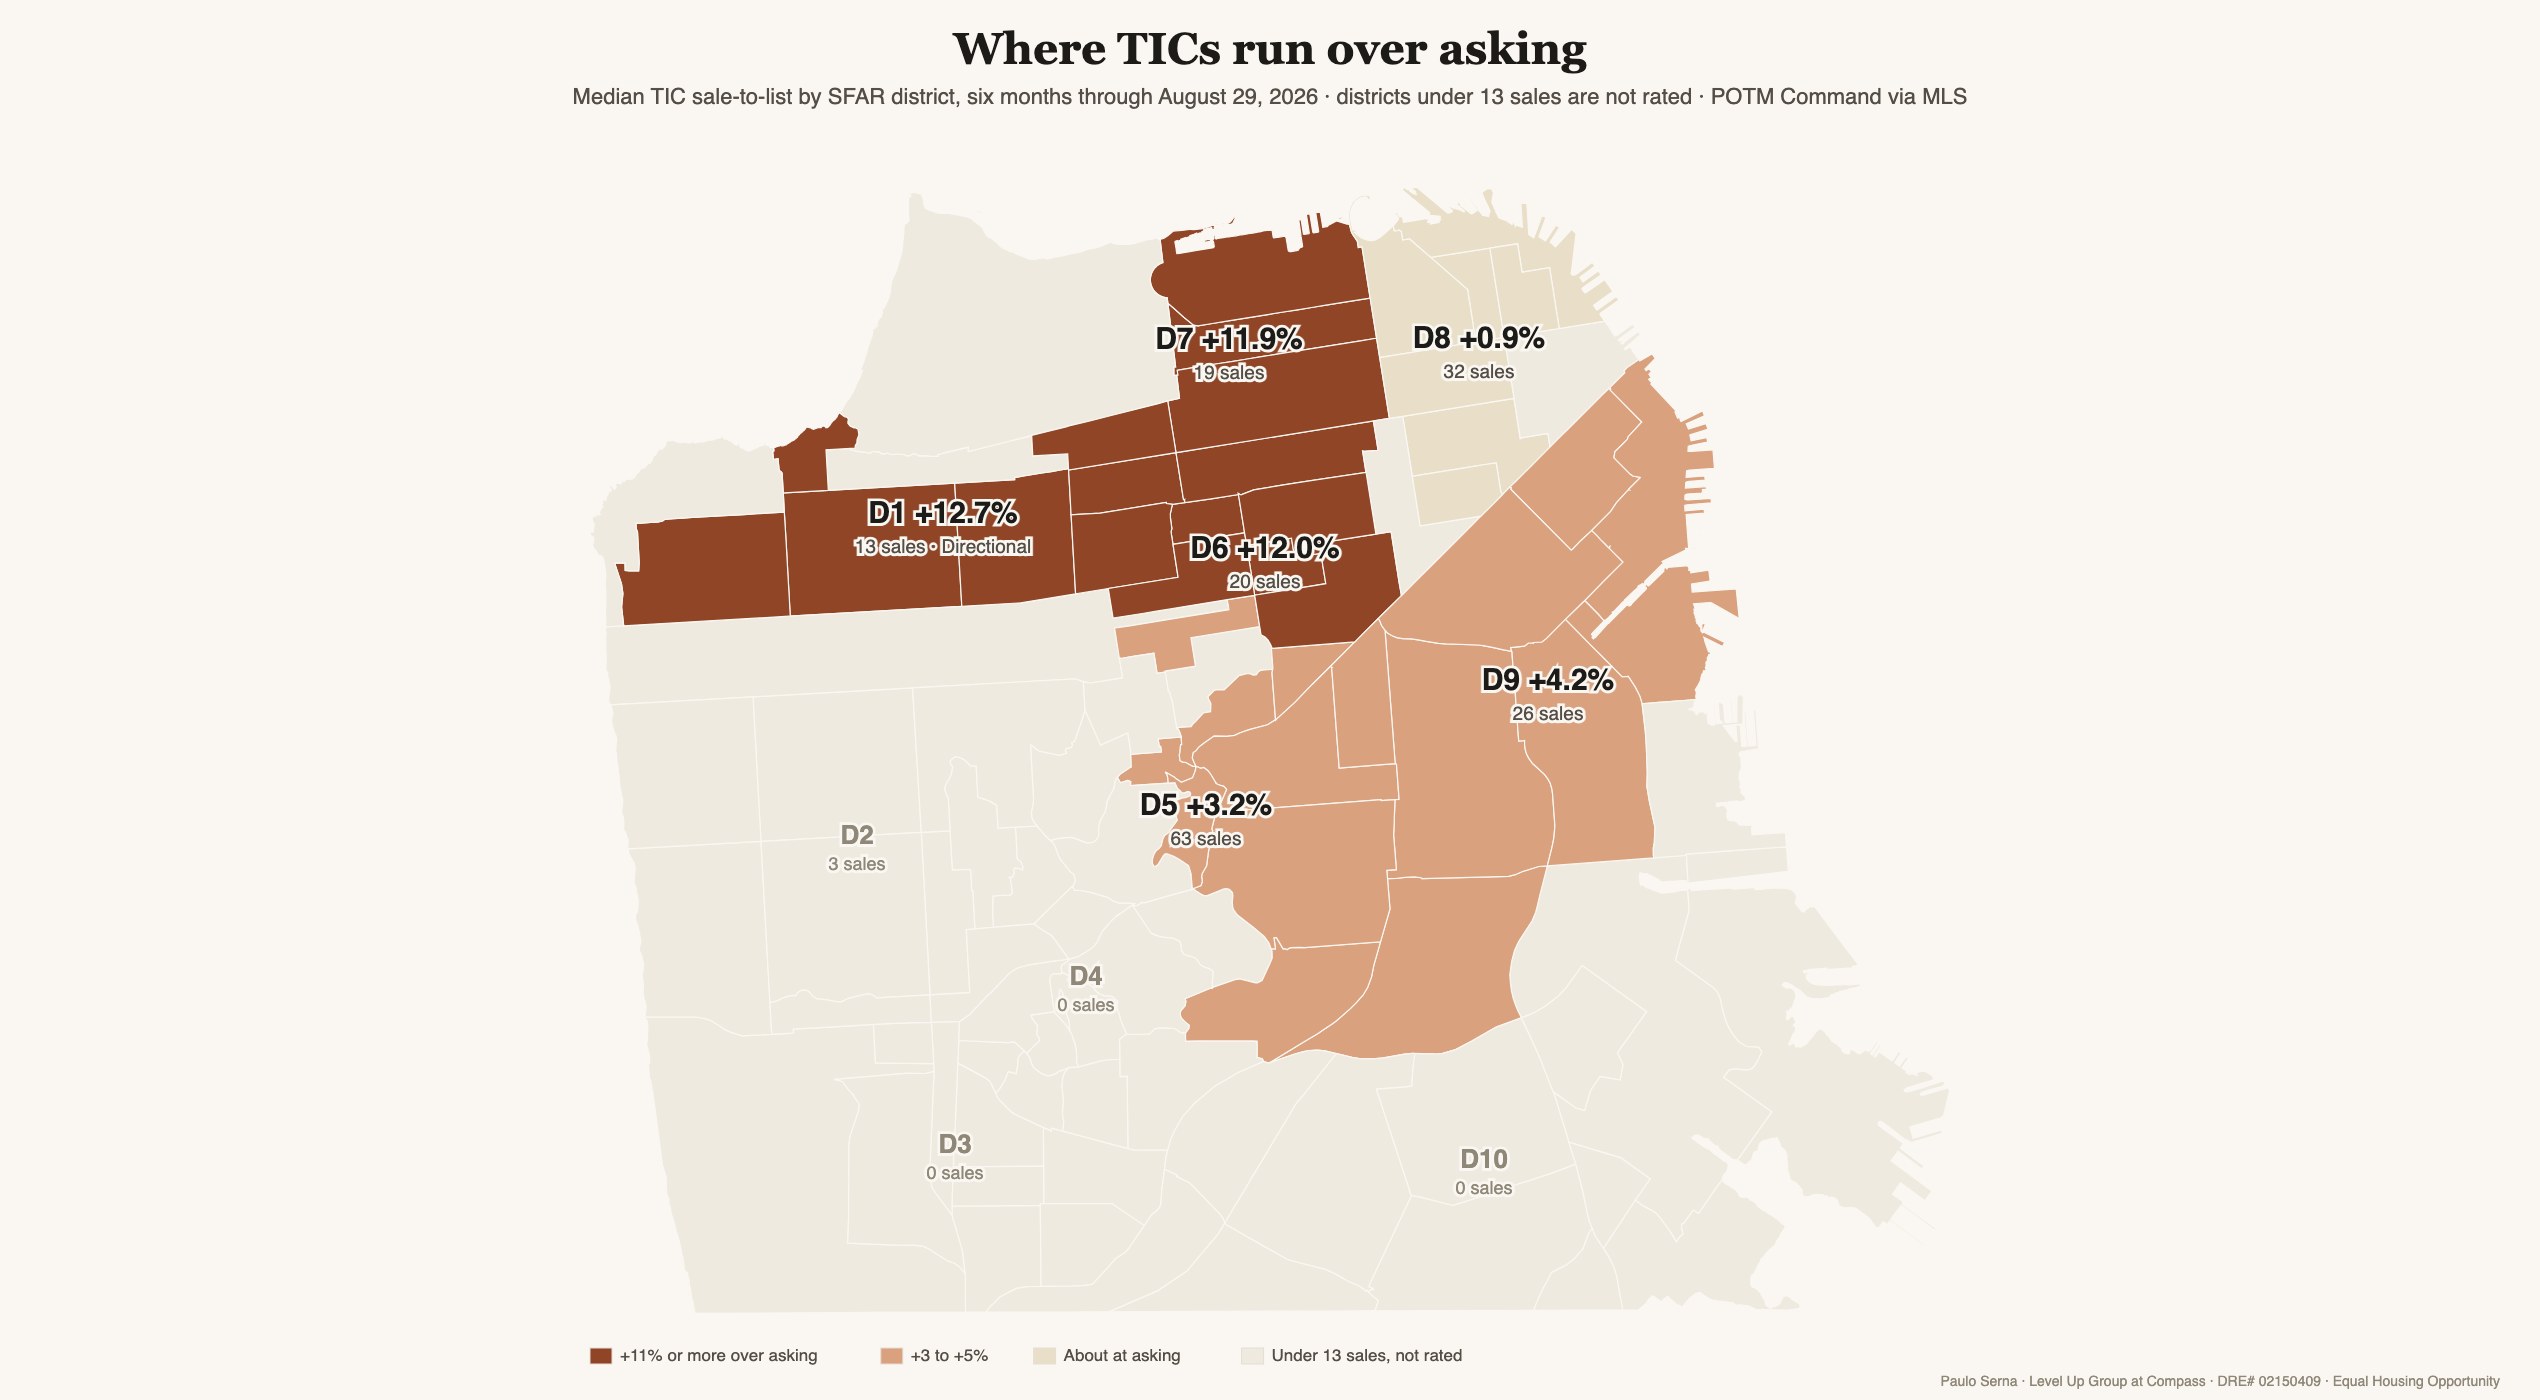
Heat and volume are not in the same place. More than a third of the city's TIC sales, 63 of them, closed in District 5, and that district's median was a mild +3.2%. Noe Valley is where I get stuck. Its condos ran +16.6% over the same six months while its TICs closed at asking on 19 sales. Sixteen points, one neighborhood, two attached products. Small samples move around, so I would not build a theory on it, though I do not want to wave it away either.
Using this in practice
If condos have priced you out of the neighborhoods you want, the TIC is the discount door, and the discount is real. Roughly 10% per square foot, plus about half the monthly dues. What you are trading is legal structure, not location and not light. That trade deserves to be understood properly, so I would bring in an attorney and a lender who both work in TICs before you write anything. You would be negotiating from knowledge while other buyers are still repeating folklore. One practical note. At 16 median days, there is little room to do the research after you find the flat. Line the team up first.
If you own a TIC and selling has been on your mind, the data says this is the strongest exit window in at least a decade. Close to two out of three TIC sales are clearing asking now, and no year in the last ten has sold faster. That is not an argument for rushing. It is an argument for pricing it as the competitive product it currently is, using your own subdistrict and the last six months rather than what a neighbor sold for years ago.
By the numbers
| Year, Jan 1 to Aug 29 | Sales | Median vs asking | Median days | Sold over asking | Went 10%+ over | Median $ per sq ft |
|---|---|---|---|---|---|---|
| 2016 | 152 | +2.6% | 39 | 62.5% | 21.1% | $695 |
| 2017 | 155 | +3.4% | 34 | 61.3% | 25.2% | $737 |
| 2018 | 174 | +5.6% | 29 | 67.2% | 38.5% | $863 |
| 2019 | 182 | +1.4% | 31 | 57.7% | 19.2% | $896 |
| 2020 | 139 | At asking | 35 | 43.2% | 9.4% | $899 |
| 2021 | 294 | At asking | 45 | 45.9% | 16.0% | $891 |
| 2022 | 220 | +0.1% | 34 | 51.4% | 20.9% | $892 |
| 2023 | 178 | At asking | 36 | 30.9% | 2.2% | $863 |
| 2024 | 171 | At asking | 34 | 41.5% | 15.2% | $861 |
| 2025 | 204 | At asking | 37 | 41.2% | 12.7% | $850 |
| 2026 | 219 | +2.9% | 18 | 61.2% | 34.2% | $978 |
AI Corridor Scoreboard
The condos near the new AI offices are the softest corner of the market right now. One reading on them per issue, so you can follow the turn while it happens rather than after.
| Issue | Date | Reading | Call |
|---|---|---|---|
| #21 (this issue) | Aug 30, 2026 | Still the calm end of the map. South Beach at asking on 167 sales with 29.9% over; SoMa, Mission Bay and Van Ness / Civic Center at asking; Yerba Buena 1.7% below. Meanwhile 56.6% of condos citywide now clear asking, up from 36.4% a year ago. | The negotiator's end of the market, with the floor rising underneath it. |
| #20 | Aug 25, 2026 | Two markets, one label. Corridor towers still at or below asking over the past six months (South Beach at asking on 168 sales, Yerba Buena -2.2%) while low-dues flats citywide cleared 10%+ over in 59.9% of sales. | Check the dues before you plan the offer. |
Show the 17 earlier readings
| Issue | Date | Reading | Call |
|---|---|---|---|
| #19 | Aug 18, 2026 | Where cash buys the most and shouts the least. Corridor condos ran 41.7% cash in the past 12 months, the heaviest concentration this series tracks, yet cash and financed closed at the same price, 99.2% versus 99.3% of asking. Cash's whole edge here is the clock: 20 median days on market against 39 financed. | Financed buyers give up nothing on price here; they pay in patience. |
| #17 | Aug 9, 2026 | Zero, which is the cleanest reading this scoreboard has produced. Across 368 corridor condo closings so far in 2026, not one sold $1,000,000 over asking, and the typical one closed slightly under asking: South Beach 0.7% below on 183 sales, South of Market 1.0% below on 79, Yerba Buena 2.4% below on 53, Mission Bay exactly at asking on 53. In an issue about where the overbidding is, the corridor is where it is not. | Buyer opening holds, and this issue measures exactly how wide it is. |
| #16 | Aug 6, 2026 | Flat in every window, which this issue argues is the whole point. South Beach condos read 100.0% of asking at 30, 90 and 180 days and 99.0% over the trailing year. South of Market reads 99.4, 99.8, 99.6 and 99.0. Four windows, one answer. Every house lane in this issue moved when the window moved; the corridor did not, and a segment that reads the same no matter how you slice it is a segment that is not turning. | Buyer opening holds, and now it is measured four ways instead of one. |
| #15 | Aug 2, 2026 | Unchanged at the bottom of the same ladder. This issue extended the over-asking gradient into small multifamily, and the corridor still anchors the low end: right at asking, while two-unit buildings cleared 11.7% over and houses 23.8%. The ordering is by how much a property lives like a house, and a corridor tower is the furthest thing from one. | Buyer opening holds, and this issue explains why it persists. |
| #14 | Jul 29, 2026 | Read on supply this time, not price. Citywide condo and townhome months of supply fell from 3.9 to 1.7 in a year and active listings from 772 to 480, so even the calmest lane in the city now offers less to choose from. This issue did not re-measure corridor pricing. | Buyer opening holds on price; the shelf behind it is thinner. |
| #13 | Jul 25, 2026 | Graduated to the essay. Back at asking for the first time since 2022, after three springs about 1% below it, and the clock changed: median market time fell from 38 days to 19 and the share selling over asking roughly doubled, from the low twenties to the mid forties. Price at par, speed doubled. | Negotiating room intact; the window now narrows in speed, not price. |
| #12 | Jul 21, 2026 | Still the calm corner, and it proves the point. District 9 condos, SoMa, Mission Bay, and South Beach, sold right at list, about 100%, with only 31% over asking on 836 sales, while mid-priced houses cleared 123 to 127% of list. Condos rarely get listed low to start a war, so the overbid never appears. | Buyer leverage holds where the list-low tactic is not used. |
| #11 | Jul 17, 2026 | Unmoved by the house story. While overbidding ran one tier below the trophy core, the corridor and condo core cleared near asking, and the two flat lanes the field named as spillover candidates, Hayes Valley and Lower Pacific Heights, stayed calm in closed data. | Still the clearest buyer opening in the city. |
| #10 | Jul 14, 2026 | Still soft while the headline is elsewhere. June's million-over-asking story is a west-side and central house market, not the AI-corridor towers. District 9 condos, SoMa, Mission Bay and South Beach, ran about 10% below last year even as volume climbed. Activity returns to the corridor; pricing has not. | Still the clearest buyer opening in the city. |
| #09 | Jul 10, 2026 | Still the soft floor at the halfway mark. District 9 condos, SoMa, Mission Bay, and South Beach, sold near 100% of list with only about 36% over asking on roughly 290 sales this year, while citywide houses ran near 121% of list. The widest lane in the city stays open. | Clearest buyer opportunity holds into the second half. |
| #08 | Jul 5, 2026 | Still the soft floor even as the top books records. District 9 condos, SoMa, Mission Bay, and South Beach, sold near 100% of list with heavy cash and light competition, while $5M+ houses set a decade volume record at about 112% of list on roughly 64% cash. Cash without a crowd here. | Buyer opportunity intact where the crowds are not. |
| #06 | Jun 25, 2026 | Still the calm corner while the house middle runs hot. District 9 condos, SoMa, Mission Bay, and South Beach, sold right at list, about 100%, with only 35% over asking on 300 sales, against the $1.5M to $3M house band at 122 to 125% of list. | Buyer opportunity holds where the bidding wars are not. |
| #05 | Jun 21, 2026 | Cash, not heat. Corridor condos carry heavier cash than the citywide condo average, about 42% versus 37%, yet still sell near 98.7% of list with only about 20% over asking versus 45% citywide. Cash concentrates here; competition does not. | Negotiating room for financed buyers. |
| #04 | Jun 17, 2026 | Still the soft floor while houses raced ahead. Corridor near 98 to 99% of list versus 103.8% citywide and about 123% for single-family in the last 30 days. | Buyer opportunity holds; the gap to houses only widened. |
| #03 | Jun 13, 2026 | Still the bottom of the overbid table. Corridor sale-to-list at about 98 to 99% versus 103.6% citywide, trailing year. | Opportunity intact for negotiators. |
| #02 | Jun 10, 2026 | Turning at the edges. Citywide condos hit 101.4% of list in May; inventory fell to 584 from 905. The corridor towers remain the soft end. | Window narrowing, not closed. |
| #01 | Jun 7, 2026 | Soft. Only 37 to 43% of SoMa, Mission Bay, and downtown condos sold over asking. | Clearest buyer opportunity in the city. |
- One year changed the picture. A median that sat at asking after 37 days now runs +5.8% over asking in 16 days, on 176 sales against 169 a year earlier. Sales clearing 10% or more over asking went from 13.6% to 39.8%, nearly triple, which puts TICs ahead of condos at 29.6%. The speed has no precedent in the record either: across ten years, no year posted a median under 29 days.
- Price it out and the TIC is the original low-dues flat. A similar-sized home carries a 10.4% discount, $986 per square foot where condos sit at $1,101, with reported dues of $450 a month rather than $823. The buildings are older too, a median year built of 1909 against 1989.
- Half of all TIC sales closed with a conventional loan, and among sales with reported financing only 24.7% were cash, under the 37.0% condos posted. That retires the cash-only story. Fractional financing for TICs is a working market on terms of its own, which is a question for a lender who handles them regularly.
- Noe Valley is the open question: TICs closed at asking on 19 sales while Noe condos ran +16.6%. More broadly the geography inverts the condo map, with heat in Districts 6, 7 and 1, the Marina at +17.8% on a Directional 9 sales, and the volume center, District 5, sitting at +3.2%.
- Volume says stable niche rather than fad or fade. Every year since 2016, the 2021 spike aside, the city closed 232 to 326 TIC sales, and 2026 is pacing near the top of that band. It stays the discount door into the neighborhoods buyers actually want.
Every San Francisco neighborhood has its sale-to-list, market time and inventory in the market explorer, each carrying its own reliability label. If a TIC listing has your attention, I would read its subdistrict there first, then put the attorney and lender in place before you write anything.
Methodology and sources
Source: POTM Command, governed MLS analytics, queried August 30, 2026. All current figures cover closed sales from March 3 through August 29, 2026; year-ago figures use the identical window in 2025. Counts: 176 TIC sales now, 169 a year ago, 1,364 condo and townhouse sales now. Every figure is an exact median, never an average. Sale-to-list is the ratio of sold price to final list price. Dues are reported on 144 of the 176 TIC sales and financing on 158; both shares use the reported denominator only, and unreported sales are never assumed. The decade table and chart compare January 1 through August 29 of each year, 2016 through 2026, so the year-to-date figures (2026 at +2.9% over asking) sit beside the trailing six-month figures (+5.8%) without contradiction; annual year-to-date samples run 139 to 294 sales. District figures at 13 or more sales meet at least the Directional reliability threshold for this window; the Marina (9 sales) and North Panhandle (5) are labeled in the text and read accordingly. Houses and 2-4 unit buildings are excluded throughout. General information, not legal, lending or tax advice: TIC ownership and financing have real legal and lending differences from condominiums, and the right professionals for those questions are a TIC-experienced attorney and lender.
Level Up Market Intel
What does this mean for your home, or the one you want?
The page above is the data and the context. What it means for one address, one budget and one timeline is a conversation. Sophia reads this market every day.